

BazPay covers five regulated markets on one contract
Sponsored content. This article was supplied by a third party and Business Money has been paid to publish it.
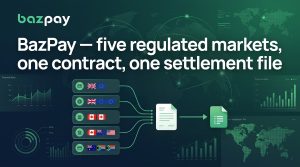 Every new market a merchant enters usually arrives with its own acquiring agreement, settlement account, reporting format and compliance annex. By the fourth country, finance is closing four batches in four layouts and engineering is maintaining four integrations that do the same job.
BazPay starts from the opposite premise. BazPay underwrites merchants in the European Union, the United Kingdom, Australia, Canada and New Zealand, and puts all five markets behind a single REST API, one balance and one webhook stream. Thirty-seven card and alternative payment methods clear on that one contract: seven card schemes, seventeen bank rails, four wallets, four BNPL providers and five direct debit schemes.
What one contract actually covers
Coverage reads market by market, because the pay-in method and the pay-out rail differ in each one:
- European Union:iDEAL, Bancontact, BLIK and EPS in their home markets; SEPA and SEPA Instant on the payout leg.
- United Kingdom: pay by bank at checkout, Faster Payments and BACS for disbursement.
- Australia: PayTo and least-cost-routed eftpos in, the New Payments Platform and Osko out.
- Canada:Interac Debit at checkout, Interac e-Transfer for payouts.
- New Zealand:account-to-account collection, domestic bank transfer out.
Licensing and reach are different things. Those five markets are where BazPay holds acquiring relationships, local settlement accounts and a signed merchant contract; acceptance is wider. A Visa, Mastercard, American Express or Cartes Bancaires credential issued anywhere authorises against the same contract and settles into the same balance, with inter-regional interchange itemised at its own rate. BazPay scores every authorisation against the merchant’s own history, sends co-badged debit down the cheaper domestic rail, and re-presents a soft decline on a second connection before the shopper sees an error — the mechanics sit in the card and APM processing documentation.
One settlement file instead of five
Multi-market growth breaks reconciliation first, so BazPay quotes interchange++ as the only model for a new merchant: the interchange the issuer keeps, the scheme fee at cost and the BazPay margin on separate lines, one line per transaction, nothing blended. Caps are set by different regulators – Regulation (EU) 2015/751, the onshored UK Interchange Fee Regulation, the Reserve Bank of Australia’s standards, and they bind interchange only, so BazPay reports scheme fees and margin separately in every market.
Data stays in region: Dublin for EU and UK traffic, Sydney for Australian and New Zealand traffic. BazPay is processor under GDPR Article 28 for merchant-instructed processing and controller for the fraud, sanctions and AML checks it must run. The operational figures BazPay publishes carry their basis: 99.98% gateway uptime on a rolling twelve months, measured at the acquiring edge, and seven consecutive PCI DSS Level 1 attestations.
Corridors are approved per merchant at underwriting, and coverage is confirmed in writing before onboarding; the solutions by business model are set out here. The question BazPay answers is not the coverage map but whether five markets can be closed from one ledger, in one format, by one finance team.